Insurance Premiums Climb Across Continental Markets
Automotive insurance premiums across Europe have risen sharply over the past two years. This trend reflects increased claim values and longer repair timelines. Insurers report that average payout amounts have grown by double digits. The financial burden is increasingly visible to drivers in urban centers.
Breaking news
 Ronna McDaniel Weighs In on GOP's Path Forward
 Market Sentiment Shifts as S&P 500 Snaps Three-Day Losing Streak
 Voters Demand Stronger Congressional Oversight of Presidential Power
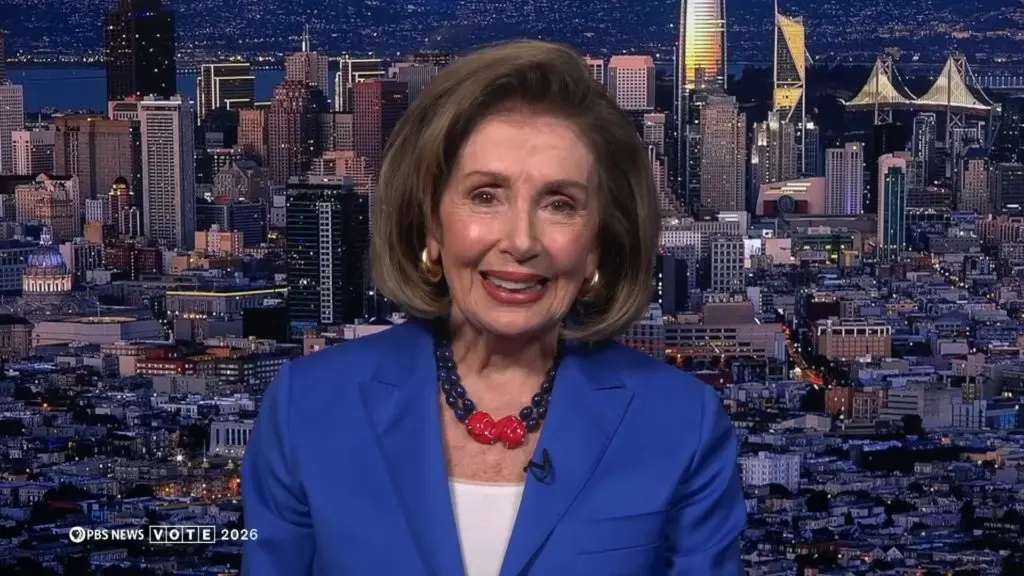 Pelosi Looks Back, Sees Democratic Triumph Ahead
Market analysts note that the surge is not uniform. Premiums are highest in regions with dense traffic and older vehicle fleets. Drivers in Southern and Eastern Europe face steeper hikes than those in Northern markets. The disparity highlights regional differences in infrastructure and vehicle age.
The primary driver of these costs is the complexity of modern vehicle technology. Cars now contain advanced sensors and electronic systems. These components require specialized tools and training for repair. Consequently, labor hours per incident have increased significantly. This technical shift is reshaping the economics of auto insurance.
Body shops are reporting higher demand for precision work.
Specialized Repairs Drive Up Labor Expenses
Modern vehicles feature aluminum frames and composite materials. These materials require specific welding and bonding techniques. Traditional steel-repair methods are often insufficient for current models. This necessitates investment in new equipment and staff certification.
The scarcity of qualified technicians is exacerbating the issue. Training programs for automotive electronics have expanded but remain lagging. In many European countries, the workforce is aging. Fewer young workers are entering the trade. This demographic gap limits capacity during peak repair periods.
For individual drivers, the impact is tangible. A minor fender bender can now result in weeks of downtime. Insurance policies often cover these extended periods. However, the cost is passed down through premiums. One example of this specialized service model can be seen in local markets, where firms like tinichigerie vopsitorie offer comprehensive repair packages.
These services integrate assessment, documentation, and premium parts replacement into a single workflow.
Impact on Consumer Behavior and Vehicle Lifespans
Higher repair costs are influencing consumer decisions regarding vehicle ownership. Many drivers are opting to keep cars longer rather than replace them. This extends the average age of vehicles on European roads. Older cars may face higher maintenance costs but avoid the risk of high-value claims on newer, expensive models.
Conversely, some consumers are shifting toward electric vehicles. EVs have fewer moving parts, potentially reducing mechanical repair needs. However, they introduce new risks related to battery replacement and charging infrastructure. Insurers are adjusting policy terms to reflect these emerging liabilities. The market is still calibrating pricing models for this transition.
Leasing companies are also affected by rising repair costs. Fleet operators face stricter requirements for vehicle condition upon return. This pressure drives up maintenance budgets for commercial entities.
The ripple effect is felt in the used car market, where certified pre-owned vehicles command higher prices. Buyers are paying a premium for verified repair histories.
Regulatory Responses and Future Projections
European regulators are monitoring the sector closely. Authorities are reviewing transparency requirements for insurance pricing. New directives aim to ensure that consumers understand how claim costs influence premiums. There is also discussion on standardizing repair protocols across borders. This could facilitate cross-border mobility and reduce regional price disparities.
Industry forecasts suggest that repair costs will continue to rise. Advances in autonomous driving technology will add more sensors and software. Each update increases the potential cost of a single accident. Manufacturers are responding by designing vehicles with modular components. This approach aims to simplify repairs and reduce waste.
The goal is to balance technological advancement with economic viability for owners and insurers alike.
The interplay between automotive design and insurance economics remains a critical area. Stakeholders are working to find sustainable solutions. For now, consumers must remain vigilant about policy terms. Understanding coverage limits and deductible structures is essential. Informed decision-making can mitigate the financial impact of rising industry costs.